Quarterly Annuity Update
Q3 2026: Pension Sponsors Capitalize on a Favorable Environment for Risk Transfer
As of September 30, 2026, our Pension Risk Transfer team executed 62 annuity placements totaling $812 million and covering approximately 10,200 plan participants.
Transaction activity reflects continued demand for both targeted and comprehensive risk transfer solutions. Of the placements completed this year, 41% supported ongoing pension de-risking strategies while 59% facilitated full plan terminations, demonstrating our ability to guide plan sponsors through a wide range of annuity transactions.
Client outcomes remain strong. Average annuity placement savings reached 4.1% through the first nine months of 2026, reflecting the value of competitive insurer bidding, disciplined transaction management and deep relationships across the insurance marketplace.
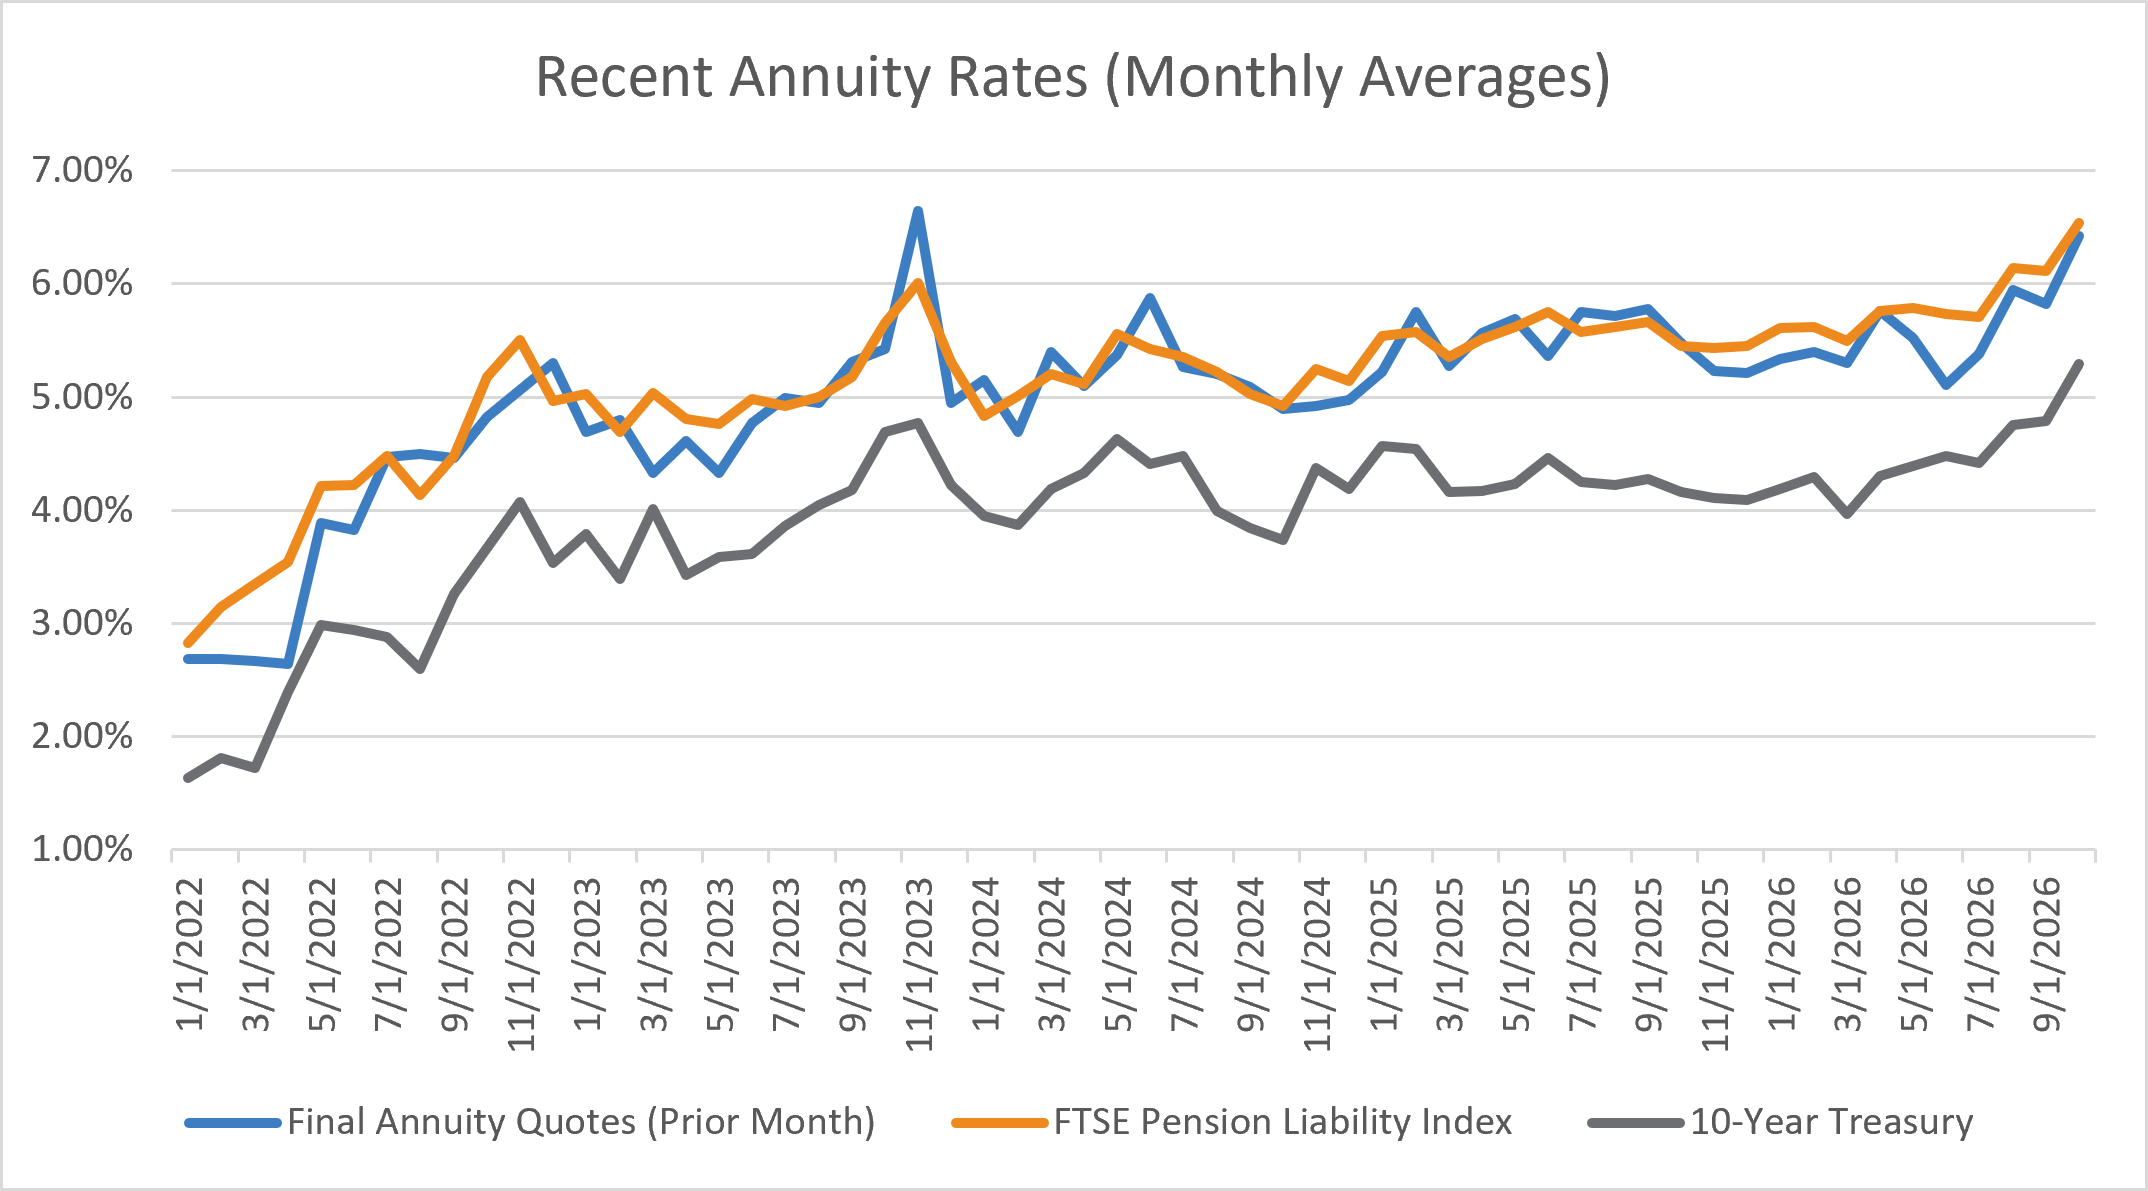
Plan sponsors are taking advantage of interest rates that remain near 20-year highs, as reflected in other long-duration financial instruments, including fixed-rate mortgages and 10-year and 30-year Treasury securities. Activity in the under $50 million market has increased compared with prior years.
USI's retirement consulting professionals continue to help organizations evaluate annuity placements, improve cost efficiency and execute pension risk transfer strategies with confidence.
Sources: FTSE Pension Liability Index Report for October 2026; Treasury.gov
Pension Plan Landscape & Industry Trends — Pension Risk Transfer
Pension risk transfer strategies help plan sponsors reduce financial exposure by shifting pension liabilities to an insurance company. A buy-out is a standard contract in the industry, transferring assets and liability from the plan sponsor to insurance company. A buy-in locks in future buy-out pricing with no accounting settlement. The assets and liabilities are maintained within the plan and held in a contract with the insurance company.
U.S. Pension Risk Transfer Demand Continues
Small to Mid-Market Placements Lead Q2 2026 Sales
| $3.0 Billion in U.S. Pension Risk Transfer Sales for Q2 2026 | Observations from Q2 2026 |
|
|
Sources: LIMRA, TruStage, Insurance Journal.
Observations from USI’s Retirement Annuity Placement Practice

Interest rates continuing to increase – lowering contract premiums
- Annuity rates follow similar trend as 10-year Treasury rate, which is at a 24-year high
Preliminary quotes are more conservative than previous years
- Interest rate changes and competition drive final premiums lower
PRT insurer TruStage (a.k.a. CUNA Mutual) had a cybersecurity attack on July 11
- No PRT monthly participant payments were impacted but customer service remains limited as company restores systems
- PRT assets were not impacted
2025 PRT market entrant Delaware Life is facing scrutiny by the SEC for not reporting related-party investments
- Rating agencies have affirmed A- Rating but outlook is negative
- Reclassified assets are not PRT premiums
Pension Plan Landscape & Industry Trends — Returns
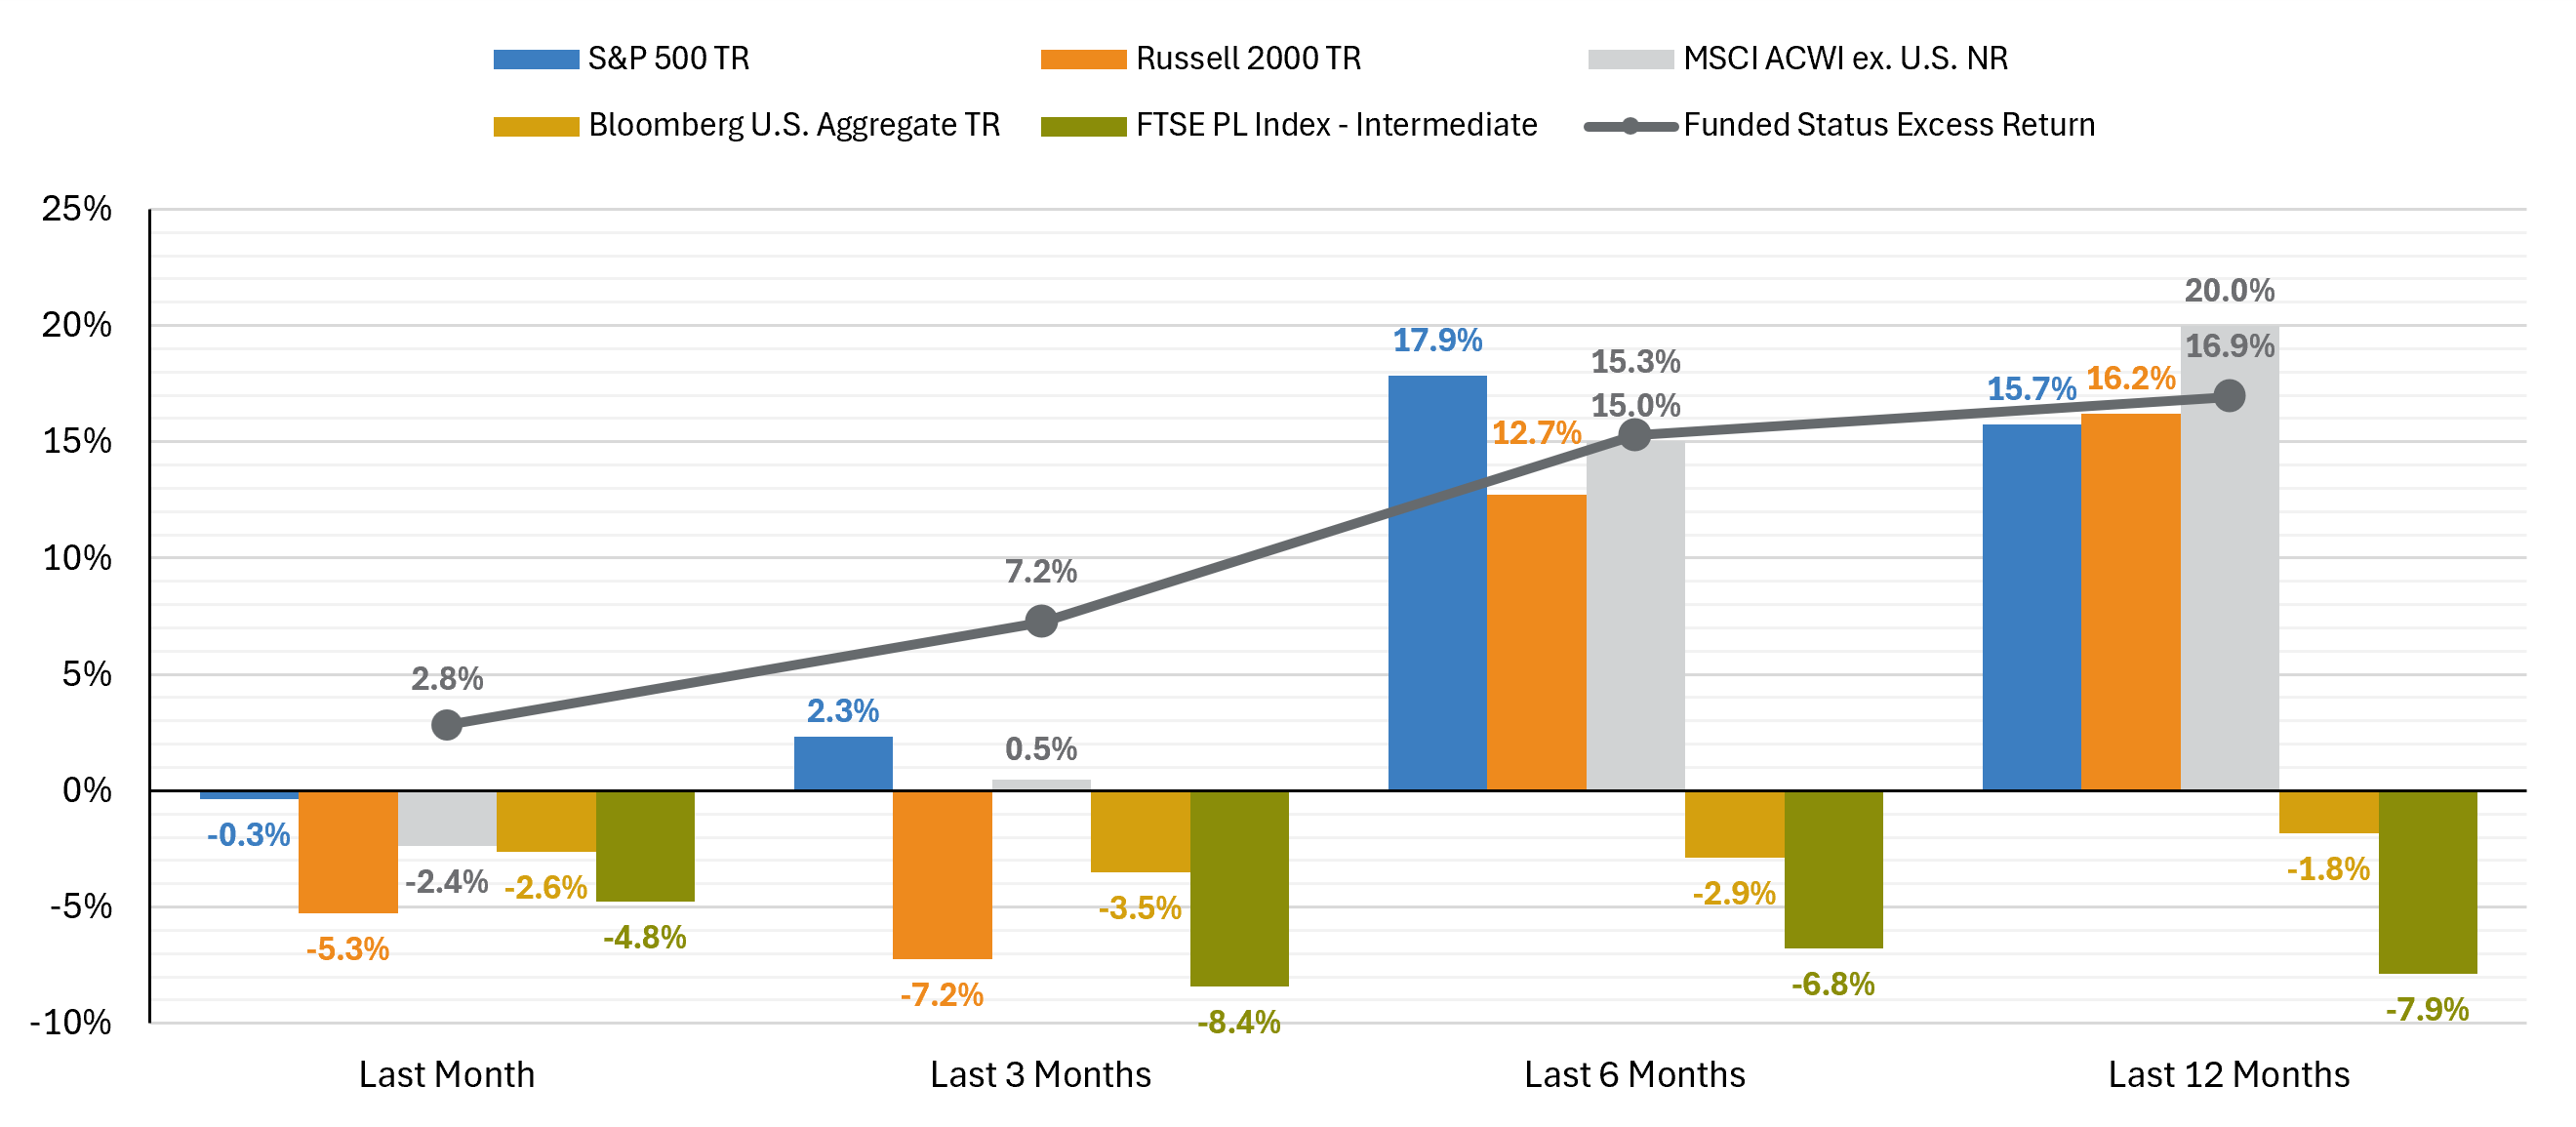
EQUITIES MIXED IN Q3 2026 |
INTEREST RATES RISING IN Q3 2026 |
|
|
PENSION PLAN FUNDED STATUS IMPROVED IN Q3 2026 |
CREDIT SPREADS HAVE WIDENED |
|
|
Market Summary for Pension Plans
Sources: Morningstar, U.S. Treasury, FTSE Pension Liability Index Report. Data as of September 30, 2026.
Pension Plan Landscape & Industry Trends — Monitoring
PENSION LIABILITY INDICES |
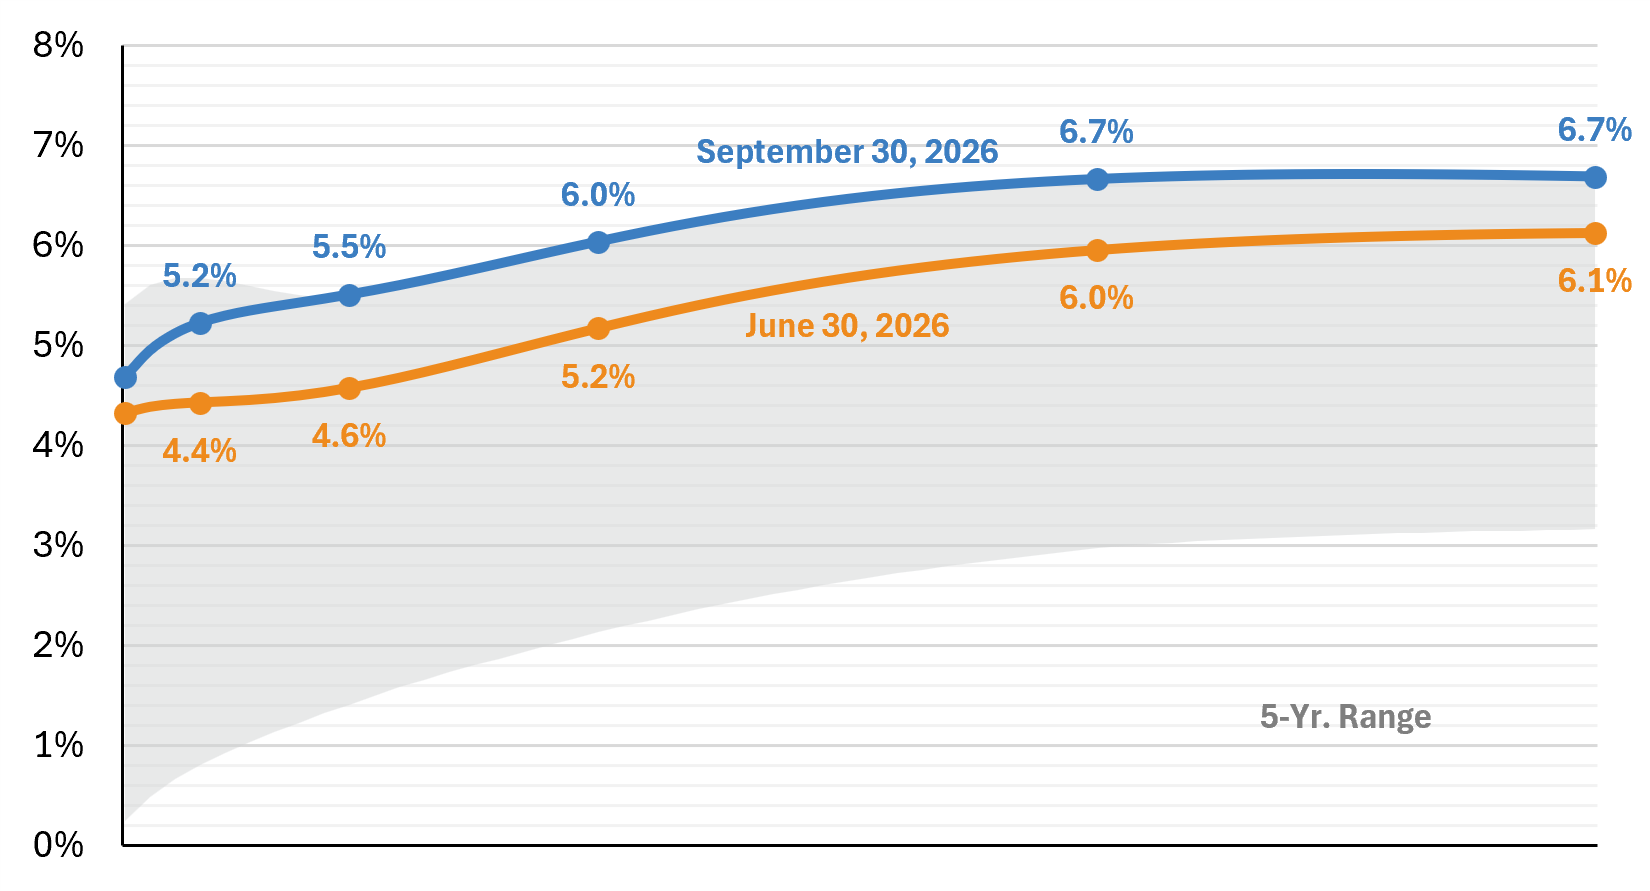
PENSION LIABILITY CURVE |
|
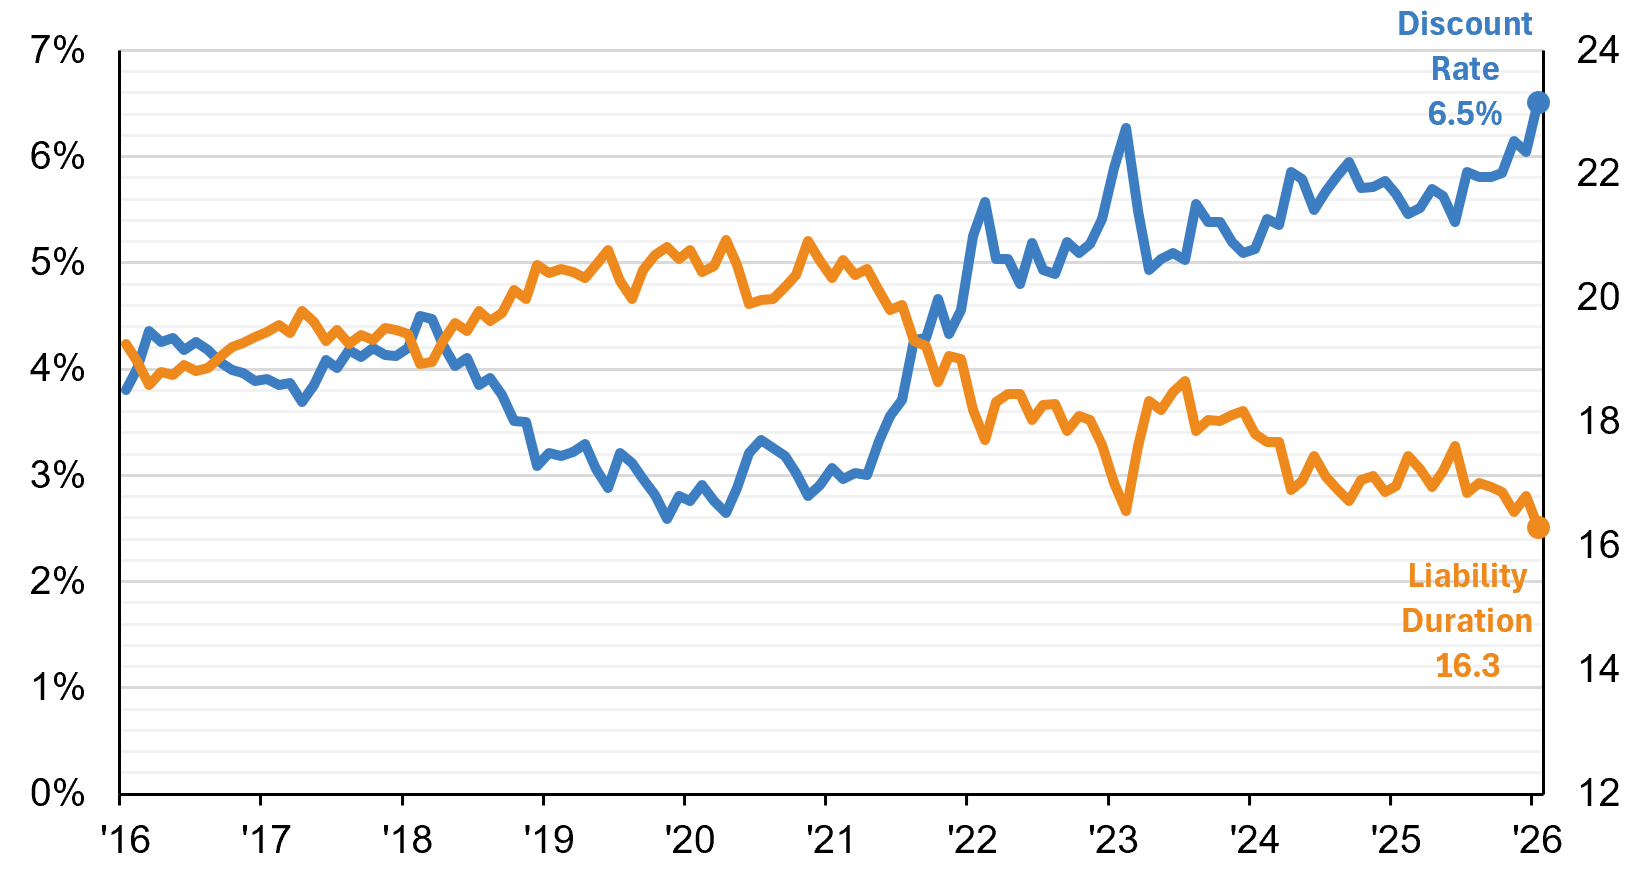
This chart tracks the Discount Rate and Liability Duration from 2016 through 2025. It highlights how interest rate changes and liability durations impact pension obligations over time. A rising discount rate typically reduces liabilities, while longer durations indicate greater sensitivity to rate changes which are key metrics for monitoring plan health. |
This curve compares pension liabilities across different maturities (6 months to 30 years) at two points in time. It shows how liabilities shift with changes in the yield curve, helping plan sponsors understand the timing and magnitude of future obligations. |
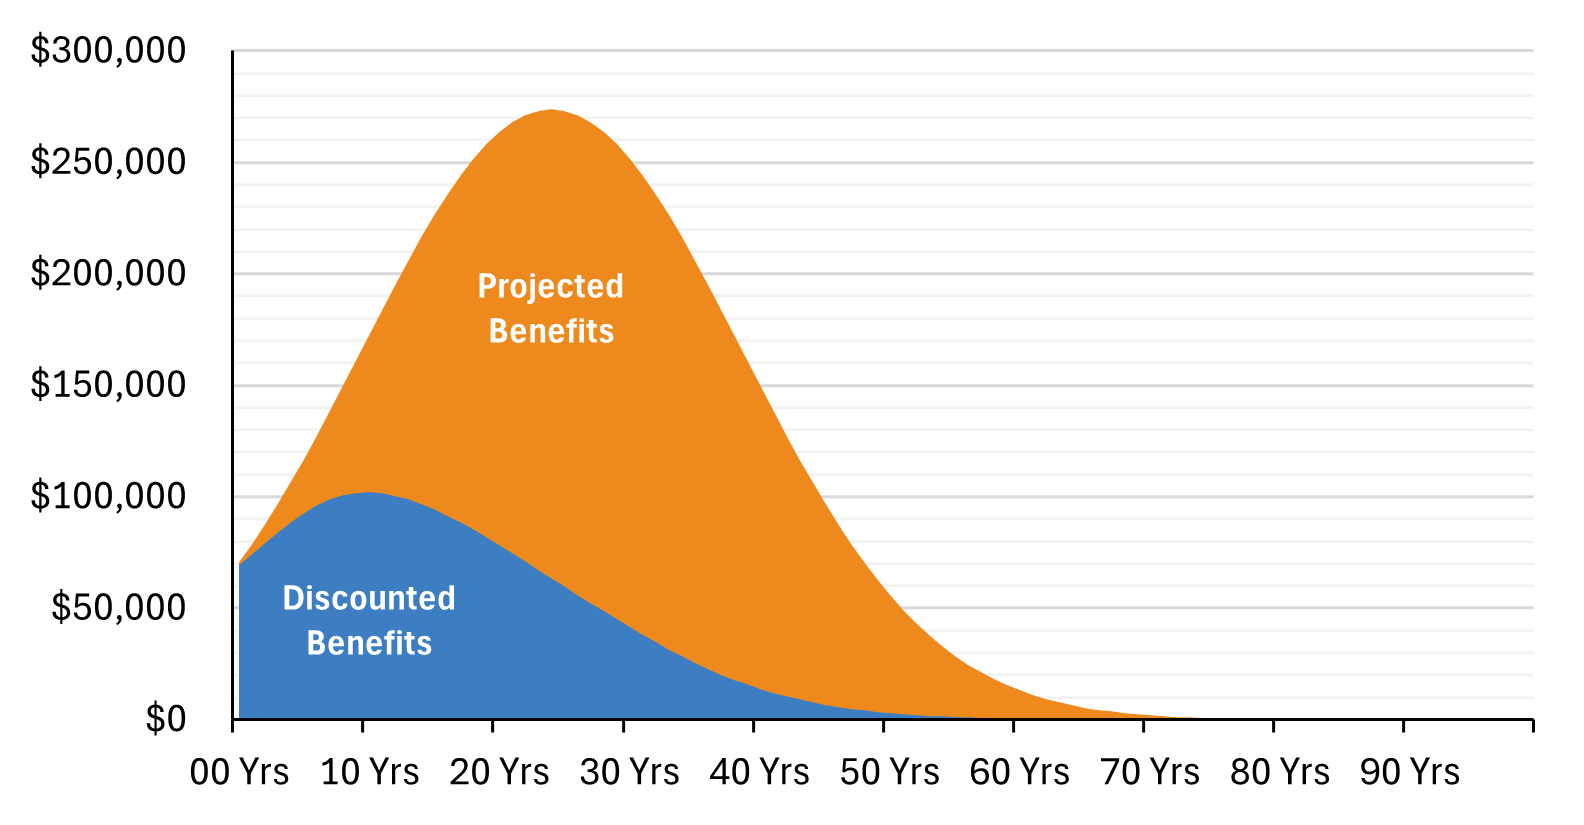
INDEX MODEL LIABILITIES |
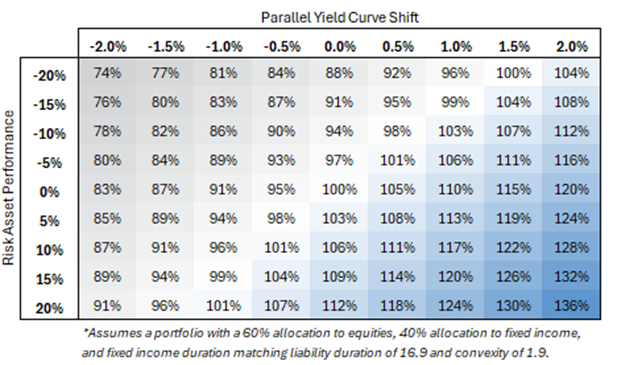
FUNDED STATUS SENSITIVITY |
|
This chart contrasts projected benefit payments with their present value across a 90-year horizon. It visualizes the long-term financial commitment of pension plans and the impact of discounting future benefits essential for evaluating funding strategies and sustainability. |
This chart helps plan sponsors understand how interest rate changes affect liabilities and funding levels which is critical for risk management and strategic planning. It shows how a pension plan’s funded status reacts to shifts in the yield curve, ranging from -2.0% to +2.0%. Each row represents a starting funded status (from 75% to 135%), and each column reflects the impact of interest rate changes. Blue cells indicate improved funding (typically from rising rates), while gray cells show deterioration (from falling rates). For example, a plan that is funded at 100% today could decline to 83% funded with a 2.0% decrease or rise to 119% with a 2.0% increase in interest rates.
|
Sources: USI Consulting Group. Data as of September 30, 2026.
STRATEGY BEFORE PLAN TERMINATION:
Surplus Management, De-Risking and the Role of Group Annuities
We hosted an informative webinar offering practical insights into the pension plan landscape and plan termination strategies.
If you couldn't attend, watch the on-demand webinar to learn about the strategy of de-risking, annuity placement and surplus management—and how these approaches impact the plan termination process.
How USI Can Help
Our retirement consulting ream is pleased to offer the opportunity to purchase single premium annuity contracts through a menu of quality insurance carriers. Our actuaries and annuity product consultants are trained to assist clients on the merits and/or limitations of a single premium annuity purchase for their specific cases. Our proactive consulting by an integrated team can provide savings that exceed an individual de-risking strategy.
To learn how we can help you, please contact your USI retirement consultant, visit our Contact Us page or email us at information@usicg.com.
Investment advice provided to the Plan by USI Advisors, Inc. Under certain arrangements, securities offered to the Plan through USI Securities, Inc. Member FINRA/SIPC. Both USI Advisors, Inc. and USI Securities, Inc. are affiliates of USI Consulting Group. | 2126.S0729.99025
Not receiving our newsletter?
Stay up to date with retirement plan updates and insights by subscribing to our email list.